
You lock in gains, you stop giving winners back, and, the part everyone repeats, your win rate goes up.
I tested it on 3,966 of my own trades. Two of those three claims are false, and the third one cost me a fortune.
The setup
I run an automated futures system with a fixed exit: each strategy takes its full target or its full stop. No partials, no breakeven moves; the trade rides to one of two doors. Over six and a half years that’s 3,966 trades, and as-traded it looks like this:
win rate: 58.0%
profit factor: 1.75
total P&L: +$98,683 (+$24.88 per trade, 1 contract)
Then I applied the textbook scale-out rule to the exact same trades: take half off at +10 points, move the runner’s stop to breakeven, let it ride to the original target. Same entries, same signals, same everything, only the exit management changed.
win rate total P&L
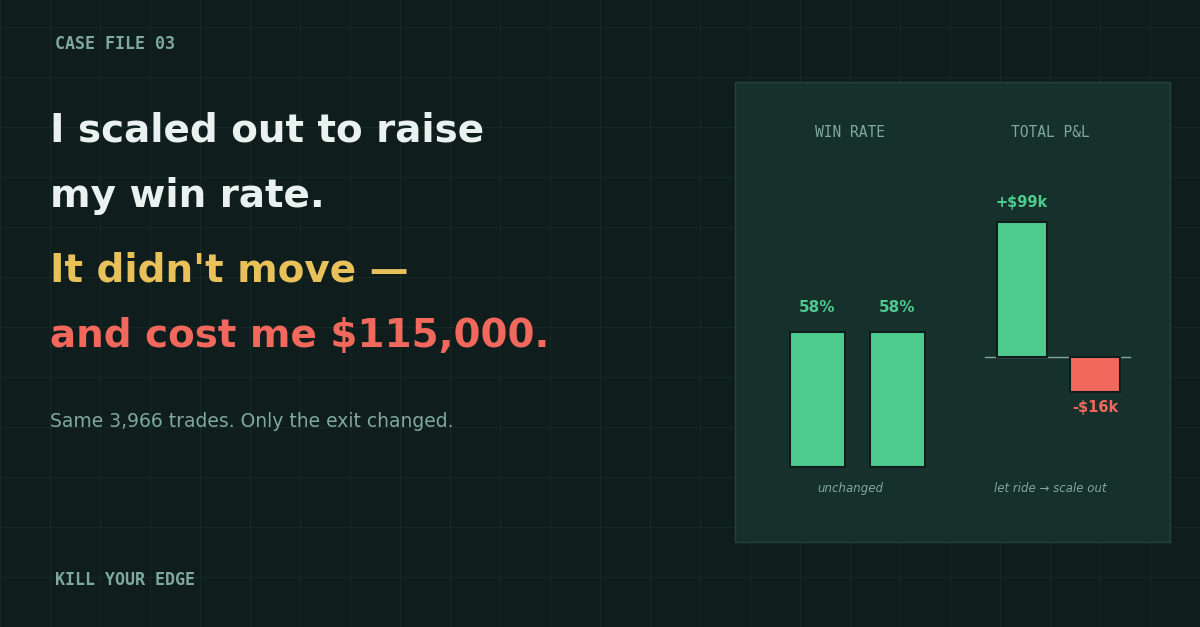
as traded 58.0% +$98,683
scale out + BE 58.0% -$16,336
A profitable system became a losing one. The same trades. −$115,020 in the exit logic alone. Twenty-nine dollars a trade, thrown away, 3,966 times.
The part nobody warns you about
Look at the win rate column again.
58.0% → 58.0%. It didn’t move. Not by a tenth of a point.
The entire pitch for scaling out is that it raises your win rate, this means you should bank more green trades, you feel better, you stay disciplined. On my data it did no such thing. The reason is arithmetic that the pitch never mentions: moving a runner to breakeven doesn’t create wins out of thin air. A trade that was going to win still wins. A trade that was going to lose, that pushed +10, triggered your partial, then reversed, now books a tiny partial gain and a scratched runner, which nets out near zero, not clearly positive. The wins you imagined converting were mostly already wins, or they land right on the line. Please note that this is regarding MY backtest and the chart that I was using.
So the win rate you were promised barely budges. But the cost is very real, and it’s hiding in the winners.
Where the $115,000 went
A profit factor of 1.75 means the winners were carrying the losers with room to spare. And in almost any real system, a small number of large winners do most of that carrying. Those are exactly the trades scaling out amputates.
When you sell half at +10 and move the rest to breakeven, the +45-point runner pays you +10 on half and gets stopped at breakeven if it wobbles on the way. You kept the small early piece and gave away the part that mattered. Do that to every winner in the book and the fat right tail, the tail the whole edge lives in, gets sheared off. The losers are unchanged. The math inverts.
The technique markets itself on the losers (”cut them, protect capital”) and stays quiet about what it does to the winners. But a positive-expectancy system is a bet on its winners. Scaling out is a tax on exactly the trades you’re trying to keep.
Why “I’ve seen it work” is true and useless
Plenty of traders swear by scaling out, and they’re not lying. On any individual trade it often feels better — you banked something, you didn’t give it all back, the runner that scratched at breakeven “saved” you. Every one of those experiences is real.
They’re also selection. You remember the runner you saved and forget the ten runners you strangled. The eye counts the trades where scaling out felt smart; the ledger weighs all of them, including the +45 you turned into +10. Six and a half years of ledger says the felt-benefit and the actual-benefit point in opposite directions.
The reproducible version
You don’t have to take my word for it. The test is simple enough to run on your own trade history:
Take your closed trades with entry, exit, direction, and size.
Compute each trade’s result as-traded, and its win rate and total.
Re-price every winner under your scale-out rule (partial at +N, runner to breakeven), leave losers as-is.
Compare win rate and total P&L.
If your system has a right tail, a few big winners doing the heavy lifting, which is most trend-following and breakout systems, you will very likely find the same shape I did: win rate barely moves, total P&L falls, and the gap is the winners you clipped.
If your win rate does jump, check why before you celebrate: it usually means your raw system
loses often and scaling out is converting a pile of small losers into scratches, which is a sign the underlying edge is thin, not that the exit is clever.
The lesson generalizes past trading: a technique that makes each decision feel better can make the whole system worse, and the feeling is not evidence. Scaling out optimizes the experience of trading; fewer gut-punches, more small wins banked. It does not optimize the outcome, which is what the un-trained eye would expect. Those are different objectives, and on my 3,966 trades they were $115,000 apart.
I write these up as I hit them — mostly places my own testing or my own instincts fooled me. If they’re useful, my email’s janheger89@gmail.com.